You still owe the bank for your car, but you have decided to sell it. Is that even allowed?
Yes, and many people do it. But selling a financed car in the UAE works differently from a normal sale, because the bank keeps a claim on the car until the loan is cleared.
If you know the term “lien” or “title” from your home country, here it is the mortgage the bank registers on your Mulkiya, the vehicle registration card. You will see it listed as “Mortgage By” next to the bank’s name.
This guide explains the 4 steps to sell a car that is under finance, the options you have, and the situation that catches many sellers by surprise. For the full sale process, see our guide to selling your car in Dubai.
The bank is registered as the mortgage holder, so experts told Gulf News that you cannot transfer ownership of a financed car until the lender has received the remaining loan balance.
The RTA also will not process the transfer while the mortgage is still active on the vehicle record.
Each bank has its own process, so the steps below are the general order, and your bank will tell you the exact documents it needs.
If you want to understand how the mortgage ends up on your Mulkiya in the first place, our guide to used car loan requirements in the UAE explains how car loans work.
A financed car cannot be transferred to a new owner until the bank settles the outstanding mortgage and releases the vehicle.
Step 1: Ask Your Bank for the Settlement Figure
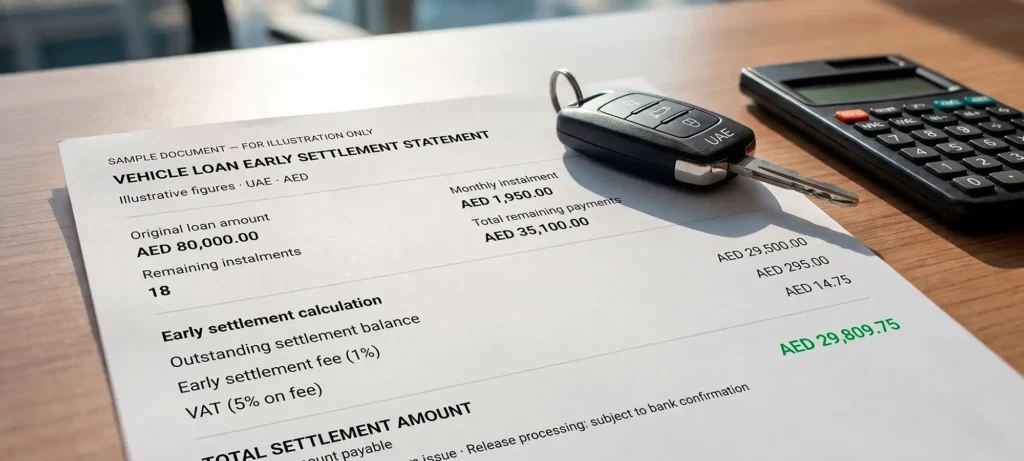
The settlement figure is the amount you must pay to close the loan today. It is not the same as the number of instalments you have left.
Call your bank or use its app and ask for an early settlement statement.
Some banks charge a fee for closing a loan early, so ask for the full figure in writing, including any fees.
Also ask how long the figure is valid and how long the bank needs to process the release after you pay.
An early settlement statement shows exactly how much you need to pay to close your car loan.
Step 2: Compare the Figure With What Your Car Is Worth
Before you agree a price with a buyer, check that the price covers the settlement figure.
If the car is worth more than you owe, the difference is yours.
If You Owe More Than the Car Is Worth
This is the situation that surprises many sellers. The bank must be paid in full, so any gap between the sale price and the settlement figure has to come from you.
Check this early, before you advertise the car or accept a deposit.
Our guide to selling your car in Dubai explains what affects a car’s value, including service history and specification.
Step 3: Settle the Loan and Get the Mortgage Release
Once the loan is paid, the bank issues a mortgage release, which may also be called a clearance letter or an NOC (No Objection Certificate).
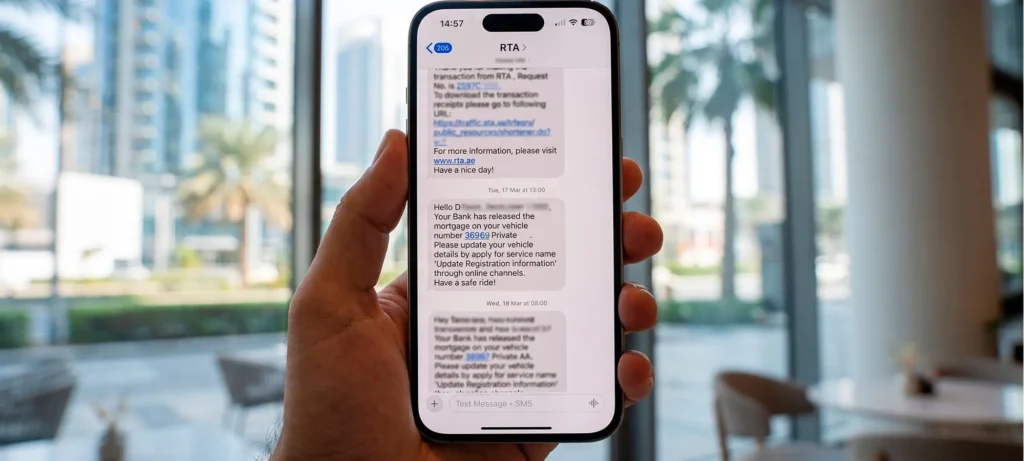
In most cases the bank sends the release to the RTA electronically, and you may receive an email or SMS confirming it.
The bank may notify you by SMS or email once the vehicle mortgage has been released.
Paying the loan and releasing the mortgage are two separate steps, so ask the bank to confirm that the release has reached the RTA.
This can happen almost instantly or take a few working days, depending on the bank, which is why it helps to start before you promise a handover date to the buyer.
Step 4: Transfer Ownership Through the RTA
When the mortgage no longer appears on the vehicle record, you can transfer ownership to the buyer at the RTA, online or in person.
Hand over the car and the keys only after the transfer is confirmed.
The full transfer process, including inspection rules and returning the plates, is in our guide to selling your car in Dubai. You can also check the official requirements on the RTA website.
Once the bank releases the mortgage and the RTA confirms the transfer, the seller can hand over the car and keys to the new owner.
Four Ways to Handle the Loan When Selling a Financed Car
Settling the loan yourself is not the only route. These are the main options.
1. Pay Off the Loan First, Then Sell
This is the cleanest route if you have the money. You close the loan, receive the mortgage release and then sell the car with no bank involved.
2. Use the Buyer’s Payment to Close the Loan
If you do not have the cash, some banks allow the buyer to pay the settlement amount to the bank, with the rest going to you.
Ask your bank whether it allows this, and do it at the bank itself so the payment can be confirmed on the spot.
3. Selling a Car That’s Still Under Loan When the Buyer Also Needs Financing
If you cannot settle your existing car loan yourself and the buyer also needs financing, ask your bank whether it can arrange the sale through a new loan for the buyer.
Find a buyer who needs a car loan and have them apply for financing. It may be worth starting with the same bank that holds your current loan. If the buyer is approved, the bank may evaluate the car and issue an LPO, setting out how the payment will be handled.
Under this arrangement, the bank may be able to use the buyer’s financing to settle your outstanding loan as part of the same transaction. After the ownership transfer, the existing mortgage can be released, and any remaining sale proceeds can be paid to you.
However, not all banks still offer this arrangement. Some require the seller to settle the existing loan and obtain a mortgage release before the buyer’s financing can be disbursed. Contact your bank before proceeding, confirm the entire process in writing, and verify the LPO directly with the bank. Do not assume that loan approval alone guarantees payment.
4. Sell to a Dealer Who Closes the Loan for You
A dealer that buys cars with a loan can settle the balance with your bank and take the car. You deal with a company instead of an anonymous buyer from an ad.
Skip the Paperwork: Sell Your Financed Car to Ready2Ride Motors
At Ready2Ride Motors, we buy cars that still have a loan.
We close the loan with your bank for you, so you are free of the debt, and then the car is transferred to us.
Yes, but the bank must release the mortgage before the RTA can transfer ownership, and how that happens depends on your bank.
It can happen almost instantly or take a few working days after the loan is settled, depending on the bank. Ask your bank for the timing before you agree a handover date with the buyer.
The bank must be paid in full, so you have to cover the difference between the sale price and the settlement figure. Check this before you advertise the car.
Yes. When the buyer’s bank approves the loan, it issues an LPO, a payment commitment. In many cases you can then transfer the car and collect the money from the bank with proof of transfer, but some banks still require your loan to be cleared first, so ask both banks.
Some banks charge an early settlement fee. Ask for the settlement figure in writing, including any fees, before you agree a price with the buyer.
Yes. We close the loan with your bank for you, so you are free of the debt, and the car is transferred to us. You can request an offer on our sell your car page.
[…] only available when there are no pending fines or bank loan. If the car is financed, our guide to selling a financed car in the UAE explains the […]
[…] you’re selling a financed car, read our guide to selling a financed car in the UAE for the settlement process, mortgage release, and options when the buyer also needs […]
Clear, practical answers for anyone buying, selling or driving a car in the UAE. From choosing between GCC and non-GCC cars to paying fines and keeping your car in shape in the heat.
Ready2Ride Motors offers a seamless used car buying experience in Dubai, with pre-inspected, accident-free vehicles and full transparency at every step. Explore our handpicked selection of GCC-spec cars and find your perfect ride today.